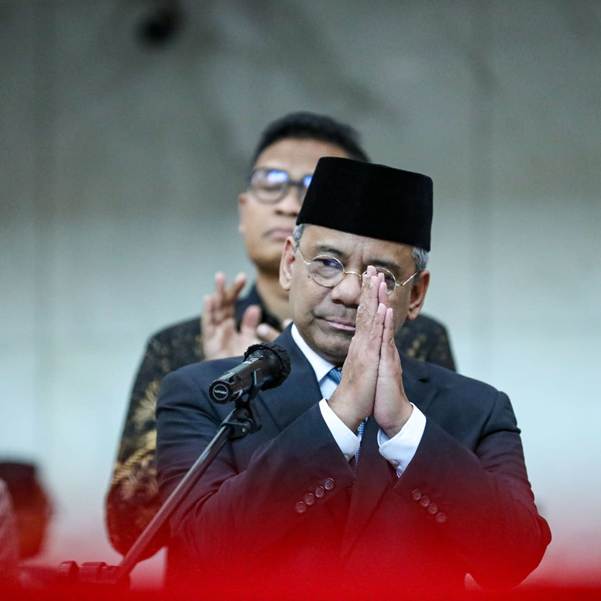
Indonesia’s Finance Minister Suahasil Nazara greeting the audience
Source: https://www.cnbc.com/2026/09/16/indonesia-finance-minister-msci-prabowo-.html
By
Satish Chandra Mishra
Dr. Satish Chandra Mishra, an economist educated at Oxford and Cambridge with senior past experience at the United Nations (UNDP), OECD, and USAID, is the Founder and Executive Director of Arthashastra Institute, Bali, Indonesia.
A Glass More Than Half Full
Indonesia’s story is one of the more remarkable transitions of our era. Within a single generation, the country has built the world’s third-largest democracy, reduced poverty from roughly a quarter of the population during the 1997–1999 Krismon crisis to 8.25 percent by September 2025, and decentralised political power to more than 500 popularly elected regional governments. Unemployment ended 2025 below 4.8 percent. Government debt stands at approximately 40 percent of GDP. Inflation ended 2025 below 3 percent. GDP growth has averaged close to 5 percent per annum for two decades, the 2020 pandemic contraction aside, and reached 5.11 percent in 2025. By any serious comparative standard, these are impressive fundamentals. But such credentials were not enough to save Indonesia from a concerted attack from the heavy hitters of the investment rating agencies and global index providers. II. The Engineered Shock In a six-week window between late January and early March 2026, Indonesia experienced one of its most severe episodes of capital market instability in recent memory. The sequence merits scrutiny. On 22 January, President Prabowo delivered a well-received address at Davos, outlining Indonesia’s investment ambitions and the Danantara architecture. Five days later, MSCI froze index changes for Indonesian stocks and warned that it could reclassify Indonesia from Emerging Market to Frontier Market status, a demotion that would oblige emerging-market index funds to sell Indonesian equities. The next day the Jakarta Composite Index (JCI) fell more than 8 percent intraday, triggering a mandatory trading halt; a second halt followed the day after, and approximately USD 80 billion in market capitalisation was erased over the two sessions. On 5 February, Moody’s revised Indonesia’s sovereign outlook to negative. Fitch followed in early March with a negative outlook. The reasons offered ranged across market shallowness, governance anxieties over the dismissal of Finance Minister Sri Mulyani, concerns about Danantara’s management, and ancillary grievances including cabinet size and the school meals programme. The timing invites scrutiny. Whether by design or by the constrained logic of global financial markets reacting simultaneously to the same inputs, the effect was a sharp public rebuke at the precise moment Indonesia was projecting confidence and soliciting capital. III.
The Credibility Problem
Any serious assessment of January 2026 must be set against the agencies’ wider record. That record is, to put it plainly, poor. The 1997–1998 Asian financial crisis is the most conspicuous example. Having failed entirely to anticipate the crisis, the major agencies then downgraded the affected economies more aggressively than the deterioration of their fundamentals warranted, amplifying panic rather than providing analytical ballast. Enron and Parmalat both carried investment-grade ratings until days before their collapses. The 2008 global financial crisis confirmed what the Asian crisis had suggested: the agencies systematically misrated vast quantities of subprime mortgage-backed securities, a finding the US Financial Crisis Inquiry Commission described as central to the financial meltdown. The conflict of interest embedded in the ‘issuer pays’ model had not been reformed — merely obscured. The structural bias toward procyclicality and herd behaviour visible in those failures is present in the January 2026 Indonesian episode. The question is not whether Indonesia has genuine structural challenges. It does. The question is whether the agencies’ interventions reflected a rigorous assessment calibrated to Indonesia’s specific historical and institutional context. The evidence suggests they did not.
The MSCI Question
A central irony of the MSCI intervention is that the structural characteristics it cited — market shallowness, concentrated ownership, limited free float — have been comprehensively documented for decades. A landmark 1999 World Bank study established that fifteen Indonesian family groups controlled 61.7 percent of total stock market capitalisation, and the single largest family group alone accounted for 16.6 percent. This architecture has been known to any serious analyst for more than twenty-five years. If the concerns were genuine and longstanding, why were they escalated into a market-destabilising public threat within days of the President’s Davos appearance, rather than addressed through the constructive regulatory engagement MSCI ordinarily employs? Indonesia’s Financial Services Authority (OJK) is aware of the free-float and transparency deficits and has set out reform targets in its Capital Market Development Roadmap. Meaningful reform of entrenched corporate ownership structures takes years, not months. A credible analytical institution would acknowledge this reality. Threatening destabilising reclassification on a politically compressed timetable serves no remedial purpose.
Indonesia Is Not Greece, and It Is Not Argentina
The spectre implicit in the agencies’ interventions is sovereign default or fiscal crisis. This possibility deserves to be examined honestly, and honestly it deserves to be rejected. Indonesia has serviced its debts in full since the rescheduling that followed the 1997–1998 crisis. Its debt-to-GDP ratio of approximately 40 percent is well within any sustainable analytical range and is far lower than that of many developed economies carrying AA or AAA ratings. Its banking sector, reformed after the catastrophic failures of 1997–1998, holds capital well above regulatory minimums. Greece’s crisis arose from fiscal excess within a monetary union that removed the exchange rate mechanism, compounded by deliberate financial engineering to obscure public finances. Argentina’s recurrent crises reflect a specific history of monetary instability and creditor disputes that bears no structural resemblance to Indonesia’s situation. Drawing implicit analogies between Indonesia and these cases through rating outlooks and index signals is not responsible analysis. Rating agencies are well-suited to assess debt default probabilities in economies with stable institutional trajectories. They are structurally ill-equipped to evaluate the political economy of systemic transformation — which is precisely what Indonesia is navigating.
Toward an Honest Dialogue Among Equals
The January 2026 shock bears the hallmarks of an intervention whose timing and framing served purposes beyond objective credit analysis. What is clear is that the effect was a significant economic penalty administered at a moment of political transition — and that the analytical justifications do not withstand serious scrutiny. Indonesia, for its part, has genuine reform obligations. Greater stock market transparency, improved free-float ratios, a clearer governance and enterprise plan for Danantara, and a persuasive medium-term fiscal framework are all within reach. These reforms should be pursued not to placate foreign rating agencies, but because well governed institutions serve Indonesia’s own citizens first. The rating agencies retain a legitimate function. Reliable, impartial sovereign assessment channels capital toward creditworthy borrowers and signals genuine fiscal mismanagement. These functions matter. But they depend on credibility the agencies have repeatedly squandered — through the Asian crisis, the corporate rating scandals of the early 2000s, and the catastrophic misratings of 2008. What credibility remains rests on market convention, not demonstrated accuracy. What is required is an honest dialogue between Indonesia and the institutions that judge it — conducted between equals rather than between examiner and examinee, and one that takes a quarter-century of demonstrated institutional resilience seriously rather than treating each governance challenge as though it occurred in an institutional vacuum. The agencies aspire to teach. Perhaps, in the process, they will learn. That would be the first step toward the trust that both sides currently lack — and that both sides genuinely need.


