The 3 Percent Deficit Rule: Theocracy as Logic

By

Satish Chandra Mishra.

Dr. Satish Chandra Mishra, an economist educated at Oxford and Cambridge with senior past experience at the United Nations (UNDP), OECD, and USAID, is the Founder and Executive Director of Arthashastra Institute, Bali, Indonesia.
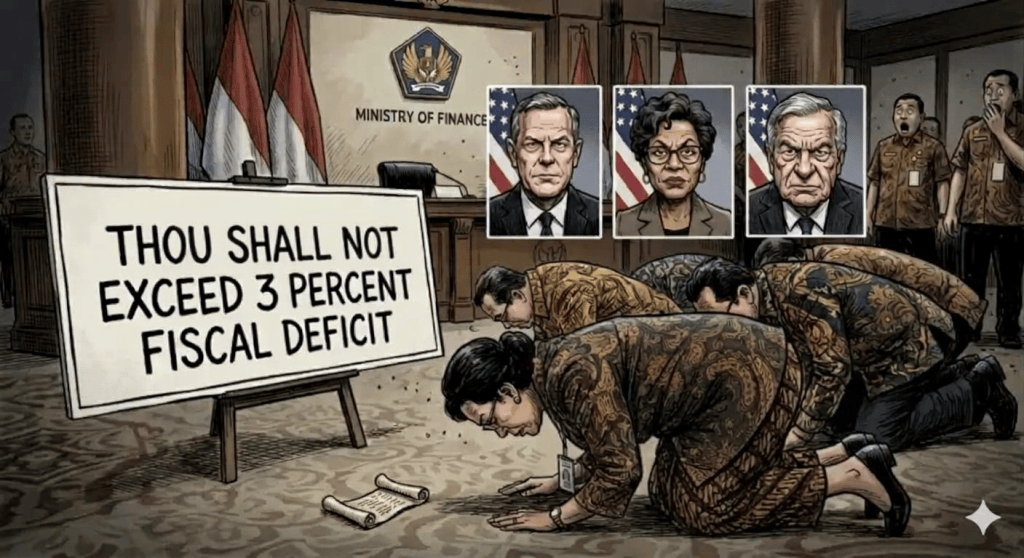


In 1981, Guy Abeille, a French budget official, invented a number. President Francois Mitterrand needed something simple to say to ministers demanding money. Abeille opted for three percent of GDP budget deficit as a working hypothesis and an expedient rule of thumb. No model produced it. No theory backs it. It was all the result of an evening’s improvisation.

No one could have predicted the future of such a hurried conjecture. The IMF and World Bank put it on the global map. They stamped that figure into loan conditions and credibility assessments. Soon a rule of thumb hardened into doctrine. Rating agencies and index makers watched it. Investors took their cue from it. A rule invented in a single fireside evening soon took on all the attributes of a new theocracy.

Ironically, it was the very countries, Germany and France, that within six years of putting it into the Maastricht treaty, waived their own penalties in 2003. Brussels suspended the whole framework again for four straight years through the pandemic and the war in Ukraine.

At the same time, economies that actually closed the gap with the rich world never let this ceiling slow them down in the first place. China ran deficits and directed state investment at whatever scale the moment required, for four decades, and grew from poverty to the world’s second-largest economy without pausing to check a number invented in Paris. South Korea’s own developmental state did not industrialize inside that constraint either. India, its own fiscal responsibility law notwithstanding, has repeatedly missed and revised its deficit targets in the pursuit of growth it judged more urgent than the arithmetic.

In the age of discontinuity unfolding before our very eyes today, it is time to understand that slow to moderate growth, and low fiscal deficit, go beyond a prudent policy choice in the world today. On the contrary, giving up on accelerated growth is the hidden danger of our own imagining and lack of national confidence.

The reasons are very familiar. We live in an age of AI, trillion dollar oligarchies and the end of a unipolar world: something humankind has never witnessed before.

In this fast evolving world, India and Indonesia together have an undeniable claim to form Asia’s second pole to China’s own rise. That claim rests on history, strategic location and economic weight: not on how faithfully either has adhered to a 3 percent budget deficit ceiling.

The 3 percent ceiling also ignores strategic emergencies. Consider defense. Indonesia has spent roughly 0.8 percent of GDP on its military for a decade, the lowest ratio in Southeast Asia, well behind Malaysia and Thailand, a fraction of Singapore’s. A nation with the largest archipelago on earth, contested waters on more than one border, and ambitions to sit at the top table of a multipolar Asia cannot get there on a budget this thin. In similar circumstances most governments would simply choose to ignore the 3 percent rule.

Nor is Indonesia in a weak position to do so. Against the world’s fifty largest economies, its deficit sits somewhere in the middle, not the end. Its public debt, near 41 percent of GDP, is much lower than the average 69 percent for the group.

Indonesia has a population still young while much of the world ages, a democracy that has produced five peaceful transfers of power since 1999, and an excellent fiscal position despite its low tax to GDP ratio. It has earned the right to be more ambitious; to stand up and be counted on the global stage.

But the growth that history demands today cannot only be high. It has also to be inclusive, or it will not hold the country together long enough to matter. A nation spread across thousands of islands and hundreds of ethnic communities does not stay unified on GDP growth alone; it stays unified when growth reaches Ambon as well as Jakarta.

Nation-building and high growth are not two separate projects competing for the same rupiah. They are the same project.

This is generational work, sustained across a change of government and a change of decade the way China’s and Korea’s own commitments were, not one finance minister’s project.

A rule invented in one evening in Paris, enforced ever since by institutions that have never themselves obeyed it, ignored outright by every economy that actually grew enough to matter, was not founded on the dry logic of economic reasoning. It was based on an inherited faith that defies both logic and the needs of the day.

In fact, Abeille’s 3 percent rule was never meant to answer any serious question at all. It was a guess, a hunch, a convenience of the moment that founded an economic theocracy.

Faith and investor confidence worked when the world stood still long enough to turn hunch into prejudice. That is not the case now.

Indonesia does not merely need a different figure to replace 3 percent. It needs to face the emerging global future with logic and reason rather than inherited faith. It is time for an open, rational debate about what kind of fiscal rule actually serves a country ready to stand inside Asia’s second pole, and to breach the technological frontier.

In 1981, Guy Abeille, a French budget official, invented a number. President Francois Mitterrand needed something simple to say to ministers demanding money. Abeille opted for three percent of GDP budget deficit as a working hypothesis and an expedient rule of thumb. No model produced it. No theory backs it. It was all the result of an evening’s improvisation.

No one could have predicted the future of such a hurried conjecture. The IMF and World Bank put it on the global map. They stamped that figure into loan conditions and credibility assessments. Soon a rule of thumb hardened into doctrine. Rating agencies and index makers watched it. Investors took their cue from it. A rule invented in a single fireside evening soon took on all the attributes of a new theocracy.

Ironically, it was the very countries, Germany and France, that within six years of putting it into the Maastricht treaty, waived their own penalties in 2003. Brussels suspended the whole framework again for four straight years through the pandemic and the war in Ukraine.

At the same time, economies that actually closed the gap with the rich world never let this ceiling slow them down in the first place. China ran deficits and directed state investment at whatever scale the moment required, for four decades, and grew from poverty to the world’s second-largest economy without pausing to check a number invented in Paris. South Korea’s own developmental state did not industrialize inside that constraint either. India, its own fiscal responsibility law notwithstanding, has repeatedly missed and revised its deficit targets in the pursuit of growth it judged more urgent than the arithmetic.

In the age of discontinuity unfolding before our very eyes today, it is time to understand that slow to moderate growth, and low fiscal deficit, go beyond a prudent policy choice in the world today. On the contrary, giving up on accelerated growth is the hidden danger of our own imagining and lack of national confidence.

The reasons are very familiar. We live in an age of AI, trillion-dollar oligarchies and the end of a unipolar world: something humankind has never witnessed before.

In this fast evolving world, India and Indonesia together have an undeniable claim to form Asia’s second pole to China’s own rise. That claim rests on history, strategic location and economic weight: not on how faithfully either has adhered to a 3 percent budget deficit ceiling.

The 3 percent ceiling also ignores strategic emergencies. Consider defense. Indonesia has spent roughly 0.8 percent of GDP on its military for a decade, the lowest ratio in Southeast Asia, well behind Malaysia and Thailand, a fraction of Singapore’s. A nation with the largest archipelago on earth, contested waters on more than one border, and ambitions to sit at the top table of a multipolar Asia cannot get there on a budget this thin. In similar circumstances most governments would simply choose to ignore the 3 percent rule.

Nor is Indonesia in a weak position to do so. Against the world’s fifty largest economies, its deficit sits somewhere in the middle, not the end. Its public debt, near 41 percent of GDP, is much lower than the average 69 percent for the group.

Indonesia has a population still young while much of the world ages, a democracy that has produced five peaceful transfers of power since 1999, and an excellent fiscal position despite its low tax to GDP ratio. It has earned the right to be more ambitious; to stand up and be counted on the global stage.

But the growth that history demands today cannot only be high. It has also to be inclusive, or it will not hold the country together long enough to matter. A nation spread across thousands of islands and hundreds of ethnic communities does not stay unified on GDP growth alone; it stays unified when growth reaches Ambon as well as Jakarta.

Nation-building and high growth are not two separate projects competing for the same rupiah. They are the same project.

This is generational work, sustained across a change of government and a change of decade the way China’s and Korea’s own commitments were, not one finance minister’s project.

A rule invented in one evening in Paris, enforced ever since by institutions that have never themselves obeyed it, ignored outright by every economy that actually grew enough to matter, was not founded on the dry logic of economic reasoning. It was based on an inherited faith that defies both logic and the needs of the day.

In fact, Abeille’s 3 percent rule was never meant to answer any serious question at all. It was a guess, a hunch, a convenience of the moment that founded an economic theocracy.

Faith and investor confidence worked when the world stood still long enough to turn hunch into prejudice. That is not the case now.

Indonesia does not merely need a different figure to replace 3 percent. It needs to face the emerging global future with logic and reason rather than inherited faith. It is time for an open, rational debate about what kind of fiscal rule serves a country ready to stand inside Asia’s second pole and to breach the technological frontier.
Indonesia’s Financial Shock of 2026: What the Rating Agencies Got Wrong

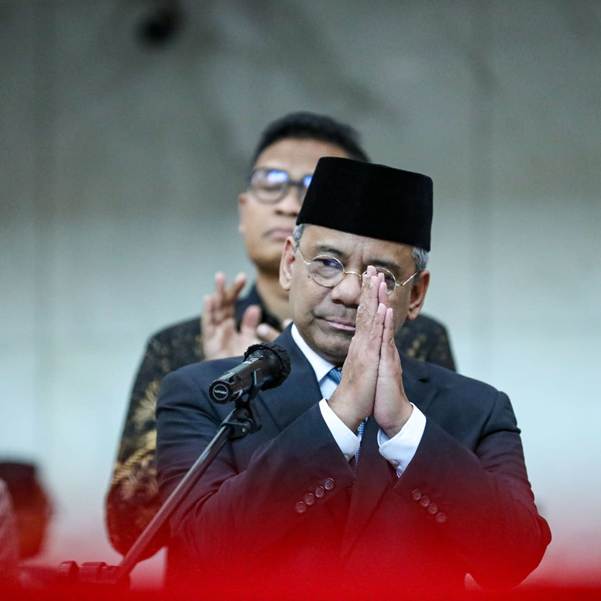
Indonesia’s Finance Minister Suahasil Nazara greeting the audience

Source: https://www.cnbc.com/2026/09/16/indonesia-finance-minister-msci-prabowo-.html


By

Satish Chandra Mishra

Dr. Satish Chandra Mishra, an economist educated at Oxford and Cambridge with senior past experience at the United Nations (UNDP), OECD, and USAID, is the Founder and Executive Director of Arthashastra Institute, Bali, Indonesia.


A Glass More Than Half Full

Indonesia’s story is one of the more remarkable transitions of our era. Within a single generation, the country has built the world’s third-largest democracy, reduced poverty from roughly a quarter of the population during the 1997–1999 Krismon crisis to 8.25 percent by September 2025, and decentralised political power to more than 500 popularly elected regional governments. Unemployment ended 2025 below 4.8 percent. Government debt stands at approximately 40 percent of GDP. Inflation ended 2025 below 3 percent. GDP growth has averaged close to 5 percent per annum for two decades, the 2020 pandemic contraction aside, and reached 5.11 percent in 2025. By any serious comparative standard, these are impressive fundamentals. But such credentials were not enough to save Indonesia from a concerted attack from the heavy hitters of the investment rating agencies and global index providers. II.  The Engineered Shock In a six-week window between late January and early March 2026, Indonesia experienced one of its most severe episodes of capital market instability in recent memory. The sequence merits scrutiny. On 22 January, President Prabowo delivered a well-received address at Davos, outlining Indonesia’s investment ambitions and the Danantara architecture. Five days later, MSCI froze index changes for Indonesian stocks and warned that it could reclassify Indonesia from Emerging Market to Frontier Market status, a demotion that would oblige emerging-market index funds to sell Indonesian equities. The next day the Jakarta Composite Index (JCI) fell more than 8 percent intraday, triggering a mandatory trading halt; a second halt followed the day after, and approximately USD 80 billion in market capitalisation was erased over the two sessions. On 5 February, Moody’s revised Indonesia’s sovereign outlook to negative. Fitch followed in early March with a negative outlook. The reasons offered ranged across market shallowness, governance anxieties over the dismissal of Finance Minister Sri Mulyani, concerns about Danantara’s management, and ancillary grievances including cabinet size and the school meals programme. The timing invites scrutiny. Whether by design or by the constrained logic of global financial markets reacting simultaneously to the same inputs, the effect was a sharp public rebuke at the precise moment Indonesia was projecting confidence and soliciting capital. III. 

The Credibility Problem

Any serious assessment of January 2026 must be set against the agencies’ wider record. That record is, to put it plainly, poor. The 1997–1998 Asian financial crisis is the most conspicuous example. Having failed entirely to anticipate the crisis, the major agencies then downgraded the affected economies more aggressively than the deterioration of their fundamentals warranted, amplifying panic rather than providing analytical ballast. Enron and Parmalat both carried investment-grade ratings until days before their collapses. The 2008 global financial crisis confirmed what the Asian crisis had suggested: the agencies systematically misrated vast quantities of subprime mortgage-backed securities, a finding the US Financial Crisis Inquiry Commission described as central to the financial meltdown. The conflict of interest embedded in the ‘issuer pays’ model had not been reformed — merely obscured. The structural bias toward procyclicality and herd behaviour visible in those failures is present in the January 2026 Indonesian episode. The question is not whether Indonesia has genuine structural challenges. It does. The question is whether the agencies’ interventions reflected a rigorous assessment calibrated to Indonesia’s specific historical and institutional context. The evidence suggests they did not.

The MSCI Question

A central irony of the MSCI intervention is that the structural characteristics it cited — market shallowness, concentrated ownership, limited free float — have been comprehensively documented for decades. A landmark 1999 World Bank study established that fifteen Indonesian family groups controlled 61.7 percent of total stock market capitalisation, and the single largest family group alone accounted for 16.6 percent. This architecture has been known to any serious analyst for more than twenty-five years. If the concerns were genuine and longstanding, why were they escalated into a market-destabilising public threat within days of the President’s Davos appearance, rather than addressed through the constructive regulatory engagement MSCI ordinarily employs? Indonesia’s Financial Services Authority (OJK) is aware of the free-float and transparency deficits and has set out reform targets in its Capital Market Development Roadmap. Meaningful reform of entrenched corporate ownership structures takes years, not months. A credible analytical institution would acknowledge this reality. Threatening destabilising reclassification on a politically compressed timetable serves no remedial purpose.

  Indonesia Is Not Greece, and It Is Not Argentina

The spectre implicit in the agencies’ interventions is sovereign default or fiscal crisis. This possibility deserves to be examined honestly, and honestly it deserves to be rejected. Indonesia has serviced its debts in full since the rescheduling that followed the 1997–1998 crisis. Its debt-to-GDP ratio of approximately 40 percent is well within any sustainable analytical range and is far lower than that of many developed economies carrying AA or AAA ratings. Its banking sector, reformed after the catastrophic failures of 1997–1998, holds capital well above regulatory minimums. Greece’s crisis arose from fiscal excess within a monetary union that removed the exchange rate mechanism, compounded by deliberate financial engineering to obscure public finances. Argentina’s recurrent crises reflect a specific history of monetary instability and creditor disputes that bears no structural resemblance to Indonesia’s situation. Drawing implicit analogies between Indonesia and these cases through rating outlooks and index signals is not responsible analysis. Rating agencies are well-suited to assess debt default probabilities in economies with stable institutional trajectories. They are structurally ill-equipped to evaluate the political economy of systemic transformation — which is precisely what Indonesia is navigating.

Toward an Honest Dialogue Among Equals

The January 2026 shock bears the hallmarks of an intervention whose timing and framing served purposes beyond objective credit analysis. What is clear is that the effect was a significant economic penalty administered at a moment of political transition — and that the analytical justifications do not withstand serious scrutiny. Indonesia, for its part, has genuine reform obligations. Greater stock market transparency, improved free-float ratios, a clearer governance and enterprise plan for Danantara, and a persuasive medium-term fiscal framework are all within reach. These reforms should be pursued not to placate foreign rating agencies, but because well governed institutions serve Indonesia’s own citizens first. The rating agencies retain a legitimate function. Reliable, impartial sovereign assessment channels capital toward creditworthy borrowers and signals genuine fiscal mismanagement. These functions matter. But they depend on credibility the agencies have repeatedly squandered — through the Asian crisis, the corporate rating scandals of the early 2000s, and the catastrophic misratings of 2008. What credibility remains rests on market convention, not demonstrated accuracy. What is required is an honest dialogue between Indonesia and the institutions that judge it — conducted between equals rather than between examiner and examinee, and one that takes a quarter-century of demonstrated institutional resilience seriously rather than treating each governance challenge as though it occurred in an institutional vacuum. The agencies aspire to teach. Perhaps, in the process, they will learn. That would be the first step toward the trust that both sides currently lack — and that both sides genuinely need.

Advertising and Consumer Behaviour: The Invisible Force Behind Our Choices

By Aunul Islam, PhD, Imperial College, London, UK

“Advertising is the art of convincing people to spend money they don’t have for something they don’t need.”
— Will Rogers

A striking illustration of this idea appears in the film The Joneses (2009), directed by Derrick Borte. The movie follows a seemingly perfect family who move into an affluent suburban neighbourhood. To their neighbours, they appear successful, stylish, and enviable. However, they are not a real family. They are part of a sophisticated marketing campaign, hired to promote luxury products simply by using them in their daily lives. As neighbours begin purchasing the same cars, clothing, electronics, and household items, the film reveals how easily consumer decisions can be influenced by social status and lifestyle aspirations. The story serves as a powerful reminder that advertising extends far beyond television commercials and billboards, often shaping behaviour in subtle and unexpected ways.

Source: Ebay.com

What Is Consumer Behaviour?

Consumer behaviour refers to the way individuals and groups select, purchase, use, and dispose of products and services. These decisions are influenced by a variety of factors, including personal preferences, cultural values, social influences, income levels, and advertising.

Businesses invest significant resources in studying consumer behaviour because understanding why people buy certain products enables companies to market them more effectively. In modern society, advertising has become one of the most powerful influences on consumer decision-making.

Creating Awareness and Interest

One of advertising’s most important functions is to create awareness. Consumers cannot purchase products they know nothing about. Through advertisements, companies introduce new products, explain their features, and communicate their benefits.

For example, before a new smartphone is released, consumers are often exposed to teaser videos, online campaigns, and social media promotions. By launch day, many people are already familiar with the product and may even be eager to purchase it.

Advertising therefore acts as a bridge between businesses and consumers, helping people discover products that may meet their needs.

Influencing Consumer Preferences

Advertising does much more than inform. It shapes attitudes, desires, and preferences.

Through attractive visuals, memorable slogans, emotional storytelling, and celebrity endorsements, advertisers create strong emotional connections between consumers and products. Many advertisements associate products with success, beauty, confidence, and happiness.

Marketing pioneer David Ogilvy famously stated:

“The consumer isn’t a moron; she is your wife.”

His quote emphasises the importance of understanding the emotions and motivations behind consumer choices. Successful advertising appeals not only to logic but also to aspiration.

As demonstrated in The Joneses, people are often persuaded not by the product itself but by the lifestyle the product appears to represent. Consumers may purchase certain brands because they wish to emulate individuals they admire or believe those products will enhance their social status.

Encouraging Immediate Purchases

Many advertisements are carefully designed to encourage quick decisions. Limited-time offers, flash sales, and exclusive discounts create a sense of urgency.

Online retailers frequently display messages such as “Only two items left” or “Offer ends tonight.” These tactics tap into the fear of missing out (FOMO), motivating consumers to act immediately rather than carefully evaluating their purchase.

While these strategies can increase sales, they can also encourage impulsive spending and unnecessary purchases.

Building Brand Loyalty

Advertising also plays a crucial role in building trust and loyalty. Repeated exposure to a brand’s message, logo, and values creates familiarity among consumers.

Well-known brands such as Apple, Nike, and Coca-Cola have spent decades establishing strong identities through consistent advertising. As consumers become more familiar with these brands, they often develop a sense of trust and preference that influences future purchasing decisions.

This loyalty demonstrates that advertising’s effect does not end when a sale is made. It can shape consumer behaviour for years.

The Negative Side of Advertising

Although advertising provides valuable information and supports economic growth, it can also have negative consequences.

One major criticism is that advertising promotes materialism. Many advertisements suggest that happiness, success, and self-worth can be achieved through owning particular products. Such messages may encourage consumers to place excessive importance on possessions rather than relationships, experiences, or personal achievements.

Economist John Kenneth Galbraith once observed:

“The individual serves the industrial system not by supplying it with savings and the resulting capital; he serves it by consuming its products.”

His statement highlights concerns that modern society often encourages consumption as a measure of success, even when individuals already possess everything they need.

Social and Environmental Consequences

Advertising can also contribute to social pressure. Through social media, influencer marketing, and personalised advertisements, consumers are constantly exposed to carefully curated images of ideal lifestyles.

Many individuals, particularly young people, feel pressure to keep up with trends and purchase products in order to fit in with their peers. This can lead to anxiety, dissatisfaction, and reduced self-esteem.

Furthermore, increased consumption creates environmental challenges. As demand for products grows, so does the use of natural resources, manufacturing activity, packaging waste, and pollution. Industries such as fast fashion are frequently criticised for encouraging consumers to replace products long before their useful life has ended.

The world depicted in The Joneses may seem fictional, but it reflects a reality in which consumer decisions are increasingly shaped by social comparison and lifestyle marketing.

Conclusion

Advertising is one of the most influential forces shaping consumer behaviour in the modern world. It informs consumers, creates awareness, influences preferences, encourages purchases, and builds brand loyalty. However, it can also promote materialism, impulsive spending, social pressure, and environmental harm.

The lessons presented in The Joneses remain highly relevant today. In an era dominated by influencers, targeted advertising, and social media, consumers are often persuaded by the lifestyles they admire rather than the products they genuinely need.

As consumers, we must learn to recognise the persuasive techniques used in advertising and making purchasing decisions in a thoughtful and responsible manner.. By understanding how advertising influences our choices, we can enjoy its benefits while avoiding its potential drawbacks.

As advertising executive Leo Burnett once noted:

“Advertising says to people, ‘Here’s what we’ve got. Here’s what it will do for you. Here’s how to get it.'”

The real challenge for consumers is distinguishing true needs from purchases that fulfill immediate emotional desires.

The 25th anniversary of 9/11 – From an American tragedy to global grief

Source: The Guardian, September 10, 2026

Today (11 September 2026) marks the 25th anniversary of 9/11. The worst terrorist attack on American soil on September 11, 2001 brought trauma and tragedy to a nation that simply could not believe that there are people in the Muslim world who ‘hate us’ to the point where a determined and deadly group was prepared to engage in ‘suicide terrorism’. Nearly, 3000 innocent lives were lost when the Twin Towers in Manhattan, NY, collapsed as two aircraft slammed into the famous buildings. In response, a vengeful superpower engaged in a global war on terror that persisted for two decades, cost trillions of dollars, and brought untold misery to millions. An American tragedy became a global tragedy.

Brown University is one of the few institutions in the USA and the world at large that has sought to assemble in meticulous detail the human and fiscal costs of the ‘post-9/11 wars.’ Here are some grim proclamations from the diligent and morally courageous research team at Brown University.

Who will hold a superpower accountable for the colossal crimes that have been committed against humanity – and crimes that continue to be committed? Only its elected officials and citizens, as voters and conscientious members of society, can fulfill such much-needed responsibilities. One wonders whether the requisite political transformation will ever take place in the USA.

Baa Baa Black Sheep – if only former UK Prime Minister Starmer read his rhymes.

By

Aunul lslam, PhD (Imperial College, London)

Starmer resigns…

Source: https://www.facebook.com/TheScotsmanNewspaper/posts/keir-starmer-resignation-in-pictures-here-are-10-photos-that-tell-the-story-of-h/1469922515165033/

There are theories that Baa, Baa, Black Sheep reflects historical wool taxes in medieval England, particularly taxes associated with the wool trade. In that reading: 

  • “One for the master” refers to the Crown or ruling authority.
  • “One for the dame” refers to a local landowner or manor.
  • “And one for the little boy who lives down the lane” is seen as the small share left for ordinary people.

However, historians don’t agree that this was the rhyme’s original meaning. The earliest printed versions do not explicitly mention taxation, and there is limited evidence directly linking the rhyme to a specific tax policy. Many nursery rhymes attract political interpretations after the fact because their simple language lends itself to symbolism. 

So it’s fair to say the rhyme has been interpreted as a commentary on heavy taxation and unequal distribution of wealth. Still, it would be overstating the evidence to say it was definitely written for that purpose. 

If former UK Prime Minister Keir Starmer read the rhyme as a warning about taking too much from producers while leaving them with too little, then it becomes a political lesson about the consequences of overburdening farmers or other productive sectors.

Yes, taxes and policy reversals (“U-turns”) are often politically damaging because they can create a sense that a government is either: 

  • Taking more from people than expected, or
  • Lacking a clear, consistent plan.

That’s one reason nursery-rhyme metaphors can resonate in political debate. If someone interprets Baa, Baa, Black Sheep as being about producers handing over much of what they earn, it becomes an easy shorthand for arguments about taxation, especially among farmers or other groups who feel overburdened. 

Of course, supporters of higher taxes may argue they’re necessary to fund public services, while critics argue they can discourage investment and productivity. Similarly, what opponents call a “U-turn” might be described by supporters as a pragmatic response to changing circumstances. 

So the  point here is less about the literal meaning of the rhyme and more about its symbolic relevance: a warning that policies affecting those who create wealth or produce goods can have significant political consequences if they’re perceived as unfair.

Public reaction to government U-turns is often mixed, but in the case of controversial tax policies affecting farmers, there was significant public and sector-specific backlash before some reversals occurred. 

  • Farmers organized protests, including tractor demonstrations in Westminster, arguing that proposed inheritance tax changes would threaten family farms and make passing farms to the next generation more difficult.
  • Rural communities and farming organizations campaigned heavily against the policy, and ministers later said they had “listened closely” to those concerns when modifying the proposals.
  • The National Farmers’ Union welcomed the later changes as a relief for many farming families, suggesting the revised policy reduced some of the anxiety created by the original proposal.
  • Critics of the government argued that repeated policy reversals created an image of indecision and poor planning. Opposition parties portrayed the U-turns as evidence that ministers had misjudged public opinion.
  • Some Labour MPs reportedly became frustrated as well, with reports of concern inside the governing party about having to retreat from policies after defending them publicly.

More broadly, U-turns tend to produce two competing reactions: supporters see them as a government listening and adapting to concerns, while critics see them as a sign that the policy was flawed from the start. The balance between those views often depends on people’s existing political outlook and the specific issue involved.

However, Starmers downfall was not only these U-turns but his undignified stance as a so called human rights lawyer towards the Gaza genocide. When he was asked about the shutting of water and electricity in Gaza, his stance was pathetic as his reply was “Israel has the right to defend itself “

The U-turn here would have earned him a lot of respect! If not protecting his position as a Prime Minister.